


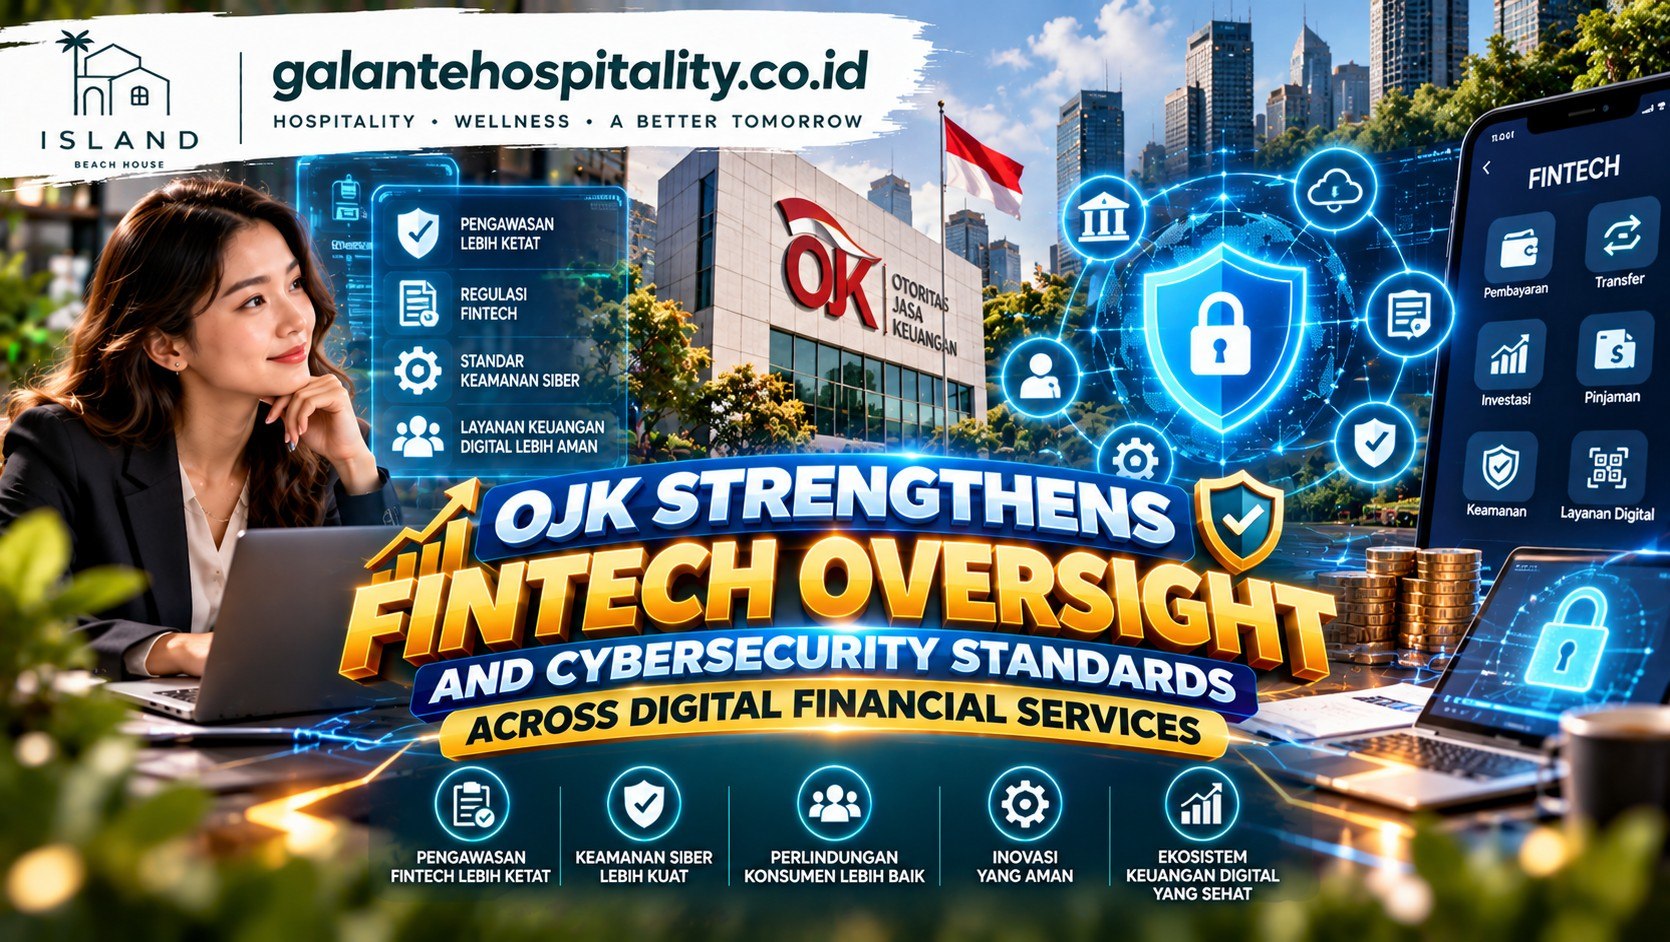

Indonesia’s Financial Services Authority (OJK) has introduced enhanced regulatory supervision guidelines and mandatory cybersecurity protocols for non-bank financial institutions, peer-to-peer (P2P) lending platforms, and digital banking operators.
The updated regulatory framework is designed to safeguard consumer data, prevent financial cybercrime, and ensure the long-term solvency of the country’s rapidly expanding financial technology (FinTech) ecosystem.
1. Pillars of the Enhanced OJK Regulatory Framework
As digital payments and online micro-lending become integral to daily commerce, OJK’s new regulations establish stricter capital standards, governance requirements, and operational risk controls for digital platforms.
+-------------------------------------------------------------------+
|               OJK FINTECH REGULATORY COMPLIANCE MANDATES          |
+-------------------------------------------------------------------+
| Compliance Pillar                 | Mandatory Requirement         |
+-----------------------------------+-------------------------------+
| Cybersecurity Audits              | Annual third-party testing    |
| Capital Adequacy Minimums         | Higher equity reserves        |
| Consumer Protection Transparency  | Transparent APR disclosures   |
+-----------------------------------+-------------------------------+
Core Compliance Obligations:
- Mandatory Cybersecurity Risk Assessments: Digital financial providers must perform regular penetration testing and maintain continuous vulnerability monitoring.
- Capital Reserve Ratios: P2P lending platforms must maintain higher minimum equity reserves to absorb credit defaults and operational disruptions.
- Interest Rate Transparency: Platforms must clearly display total annual percentage rates (APR), including all administrative fees, to prevent predatory lending practices.
External Reference: Explore regulatory updates on theOfficial Financial Services Authority (OJK) Portal(Outbound Link Suggestion).
2. Elevating Data Privacy and Anti-Cybercrime Infrastructure
Given the frequency of global financial cyberattacks, OJK requires digital platforms to align their infrastructure with national data privacy standards mandated by the Personal Data Protection (PDP) Law.
             Digital Risk Management Infrastructure
                               |
     +-------------------------+-------------------------+
     |                                                   |
     v                                                   v
[Data Encryption & Sovereignty]            [Fraud Detection Systems]
Mandatory end-to-end encryption            AI-powered transaction monitoring
and local cloud data storage               to block unauthorized access
1. Local Data Storage Requirements
Financial institutions operating in Indonesia must store critical financial transaction logs and user personal data within certified onshore data centers.
2. Automated Fraud Detection
Digital banks and FinTech lenders are required to deploy machine-learning tools to detect anomalous transaction patterns, unauthorized login attempts, and fraudulent loan applications in real time.
3. Balancing Innovation with Consumer Protection
Regulators emphasize that stricter supervision is not intended to stifle digital innovation, but rather to build sustainable trust in non-traditional financial systems.
                 +---------------------------------+
                 |  BALANCED DIGITAL ECOSYSTEM     |
                 +---------------------------------+
                                   |
   +-------------------------------+-------------------------------+
   |                               |                               |
   v                               v                               v
[Standardized Open APIs]  [Regulatory Sandboxes]   [Financial Literacy]
Enabling secure bank-to-   Testing new algorithms  Educating public on safe
fintech data sharing      in controlled environments digital borrowing
By establishing standardized Open Application Programming Interfaces (APIs), OJK enables seamless and secure data-sharing between traditional commercial banks and FinTech innovators, expanding financial inclusion while maintaining system security.
4. Strategic Outlook for Indonesian Digital Financial Services
The implementation of enhanced regulatory oversight marks a mature phase for Indonesia’s digital finance landscape. By enforcing rigorous cybersecurity standards, transparent pricing, and robust capital requirements, OJK is fostering a safer, more resilient digital ecosystem capable of attracting high-quality institutional capital while protecting millions of digital consumers.


