


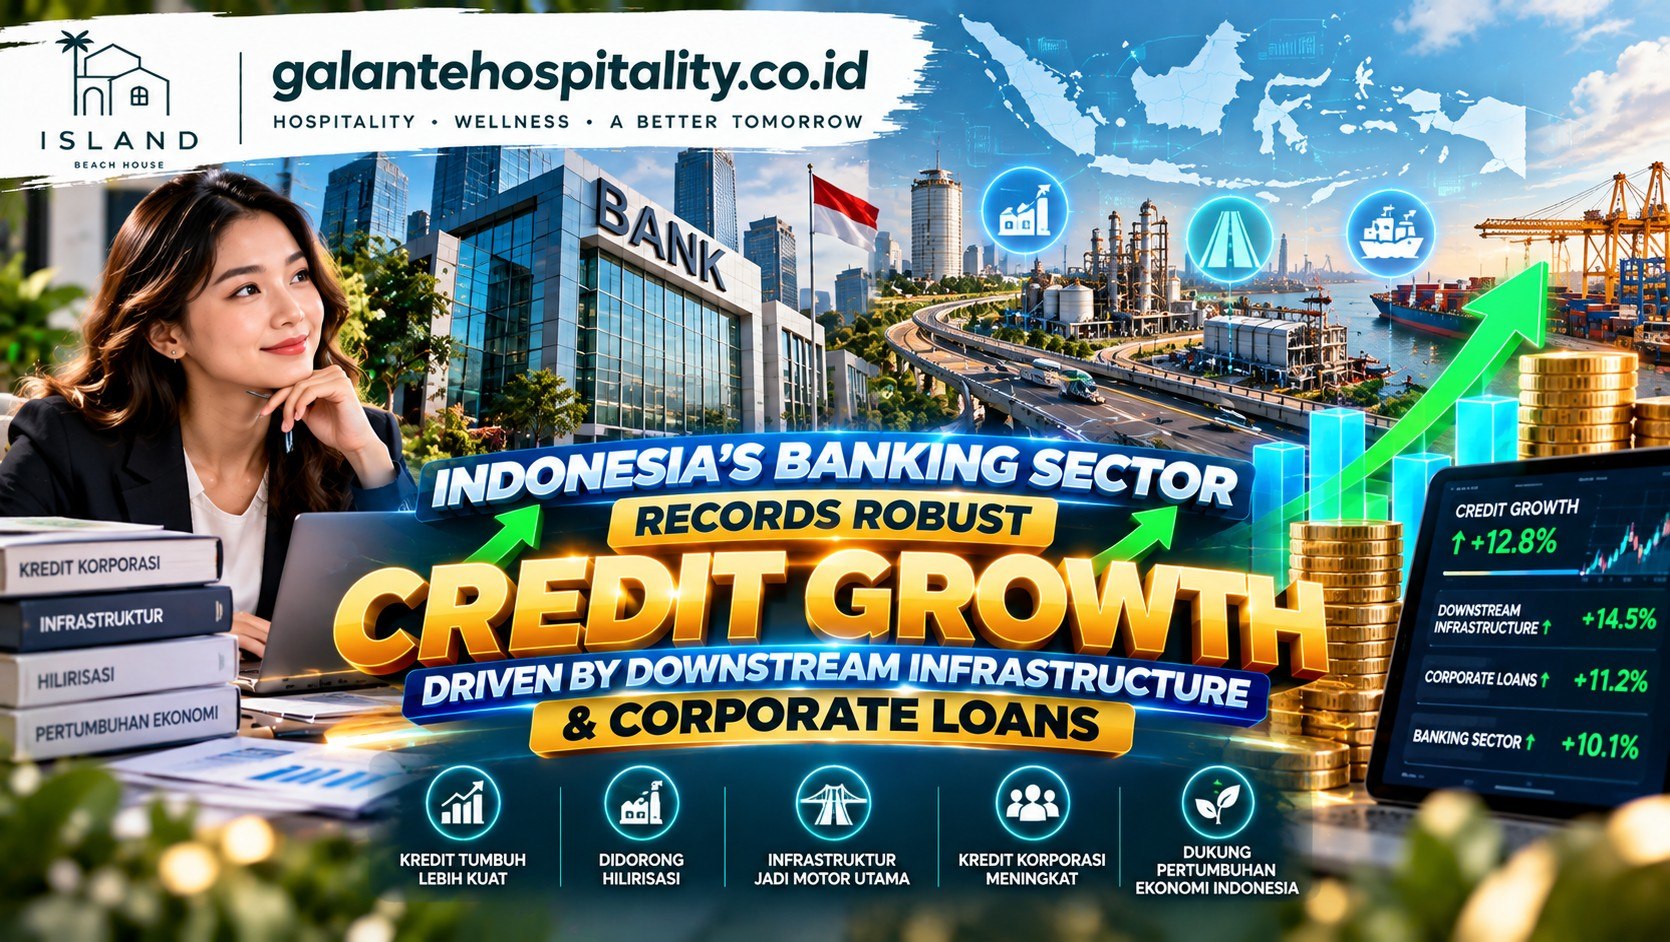

The primary catalyst behind recent credit acceleration is the national mandate for industrial downstream processing (hilirisasi). Mining, renewable energy, and heavy processing companies have secured substantial long-term syndicated loans to build domestic smelters and refining facilities.
+-------------------------------------------------------------------+
|               KEY CREDIT SECTOR GROWTH PERFORMANCE                |
+-------------------------------------------------------------------+
| Financing Sector                  | Primary Growth Driver         |
+-----------------------------------+-------------------------------+
| Industrial & Downstream Processing| Smelter construction & energy |
| Commercial & Investment Loans     | Working capital expansion     |
| Consumer Mortgages & Retail       | Stable domestic consumption   |
+-----------------------------------+-------------------------------+
Core Factors Driving Borrowing:
- Downstream Smelter Financing: Heavy investment in nickel, copper, and bauxite processing facilities requires high corporate credit lines.
- Working Capital Demand: Manufacturing enterprises are expanding operational lines to keep pace with rising domestic consumption.
- Macroprudential Support: Bank Indonesia’s Macroprudential Liquidity Incentive Policy (KLM) rewards commercial banks that lend to green, inclusive, and export-oriented industries with reduced reserve requirements.
External Reference: Review central banking statistics on theBank Indonesia Official Portal(Outbound Link Suggestion).
Maintaining Banking Sector Resilience and Credit QualityDespite rapid loan growth, financial regulators report that credit risk remains well-managed across major state-owned and private commercial banks.
                     Banking Sector Stability Indicators
                                      |
     +--------------------------------+--------------------------------+
     |                                                                 |
     v                                                                 v
[Capital Adequacy Ratio (CAR)]                        [Non-Performing Loans (NPL)]
Maintained comfortably above 25%,                      Gross NPL kept low below 2.3%,
providing strong shock absorbers                       indicating disciplined underwriting
1. Controlled Non-Performing Loans (NPL)
The industry’s gross NPL ratio remains comfortably below the regulatory ceiling of 5%. Commercial lenders have applied prudent risk management frameworks and strict collateral assessments when underwriting large-scale infrastructure loans.
2. Strong Provisioning Reserves
Indonesian banks continue to maintain conservative coverage ratios against potential loan impairments, preserving balance sheet strength against external economic shocks.
3. Financial Inclusivity and SME Credit Allocation
Alongside corporate lending, the government continues to enforce policies designed to expand credit access for micro, small, and medium enterprises (MSMEs) through subsidized credit programs like Kredit Usaha Rakyat (KUR).
                 +---------------------------------+
                 |   BALANCED CREDIT ALLOCATION    |
                 +---------------------------------+
                                   |
   +-------------------------------+-------------------------------+
   |                               |                               |
   v                               v                               v
[Large Corporate Loans]   [Subsidized MSME Loans]   [Digital Micro-Financing]
Funding downstream        Government-backed KUR     FinTech collaboration
infrastructure projects    supporting small trades   expanding regional access
Commercial banks are collaborating with digital technology partners to streamline credit scoring for micro-borrowers, reducing collateral hurdles and speeding up loan disbursement times for rural businesses.
4. Outlook for National Banking Performance
Industry analysts anticipate that credit demand will remain buoyant throughout the upcoming fiscal year. Supported by a stable benchmark interest rate environment, prudent banking regulations, and continued state investment in strategic industrial supply chains, Indonesia’s banking sector is set to remain a key engine of national economic growth.


